Buying your first home in California is an exciting milestone, but it can also be one of the most significant financial decisions you will ever make. Between rising housing costs, mortgage requirements, property inspections, and unfamiliar legal documents, the process can feel overwhelming.
For first-time homebuyers in Silicon Valley, including Menlo Park, Palo Alto, Los Altos, and surrounding communities, the challenges can be even greater because home prices are substantially higher than in many other parts of the country.
Fortunately, purchasing your first home does not necessarily require a 20% down payment, and California offers several programs designed to help qualified buyers overcome financial barriers.
This guide explains the California home buying process in 2026, including how much money you need, available mortgage programs, first-time buyer assistance, important inspections, and the steps involved in closing escrow.
1. Are You Ready to Buy Your First Home in California?
Before exploring homes for sale, the first step is determining whether buying a home makes sense for your financial situation and long-term plans.
Homeownership can provide stability, an opportunity to build equity, and greater control over your living environment. However, it also involves recurring expenses and financial responsibilities that renters may not experience.
Ask yourself the following questions:
- Do I have a stable and reasonably predictable income?
- Have I saved enough for a down payment and closing costs?
- Can I comfortably afford the monthly mortgage payment?
- Have I accounted for property taxes, insurance, utilities, and maintenance?
- Do I have emergency savings available after purchasing?
- Do I plan to remain in the home long enough to justify the transaction costs?
Rather than focusing exclusively on whether home prices or mortgage rates might rise or fall, buyers should begin by evaluating what they can comfortably afford today.
2. How Much Down Payment Do You Need to Buy a House in California?
One of the most common misconceptions among first-time homebuyers is that purchasing a home requires a 20% down payment.
Although a 20% down payment can offer financial advantages, many qualified borrowers can purchase a home with considerably less.
The minimum down payment depends on the mortgage program, property type, borrower qualifications, and lender requirements.
Mortgage Type | Potential Minimum Down Payment |
|---|---|
Conventional loan | As low as 3% for eligible borrowers and programs |
FHA loan | As low as 3.5% for eligible borrowers |
VA loan | Potentially 0% for eligible borrowers |
USDA loan | Potentially 0% for eligible properties and borrowers |
Jumbo mortgage | Varies by lender and borrower qualifications |
For example, consider a buyer purchasing a $900,000 home:
- 3% down payment: $27,000
- 5% down payment: $45,000
- 10% down payment: $90,000
- 20% down payment: $180,000
These examples illustrate down payment amounts only. Closing costs, mortgage insurance, lender requirements, and other expenses must also be considered.
Some low-down-payment programs have loan limits, income restrictions, mortgage insurance requirements, or other eligibility conditions.
3. What Are the Best First-Time Home Buyer Programs in California?
California offers several mortgage and down payment assistance programs through the California Housing Finance Agency (CalHFA) and other participating organizations.
These programs can be particularly useful for qualified buyers who have sufficient income to make mortgage payments but have difficulty saving a large down payment.
CalHFA MyHome Assistance Program
The CalHFA MyHome Assistance Program provides eligible first-time homebuyers with a deferred-payment junior loan to help cover a down payment and/or closing costs.
For qualifying FHA transactions, MyHome can provide assistance of up to 3.5% of the purchase price or appraised value, whichever is less.
For qualifying conventional transactions, assistance can be up to 3% of the purchase price or appraised value, whichever is less.
The assistance is generally structured as a subordinate loan, not a grant. Repayment requirements apply under the program terms.
Eligibility requirements include applicable income limits, owner occupancy, first-time buyer qualifications, and homebuyer education.
California Dream For All Shared Appreciation Loan Program
The California Dream For All Program is designed to assist eligible first-generation homebuyers with down payment and closing costs.
Under the 2026 program, assistance can reach up to 20% of the purchase price, subject to a maximum of $150,000 and other program limitations.
Unlike a traditional grant, Dream For All is a shared appreciation loan. When a qualifying repayment event occurs, the borrower generally must repay the original assistance plus a specified share of the home's appreciation.
The program requires eligible borrowers to participate in a voucher registration and selection process.
The 2026 registration round has already taken place, and vouchers were released in May 2026. Buyers should check CalHFA's official website for future funding rounds rather than assume applications are continuously available.
Other California and Local Assistance Programs
Additional assistance may be available through participating lenders, local housing agencies, and organizations such as the Golden State Finance Authority.
Program requirements vary based on location, income, loan type, occupancy, and available funding.
In high-cost communities such as Menlo Park, Palo Alto, and Los Altos, buyers should verify whether their income and proposed purchase price fall within the applicable program limits.
The California Department of Real Estate provides additional resources for first-time homebuyers.
4. Who Qualifies as a First-Time Homebuyer in California?
You may qualify for certain first-time homebuyer programs even if you previously owned a home.
For many CalHFA programs, a first-time homebuyer generally includes someone who has not owned and occupied a primary residence during the preceding three years and has not lived in a home owned by a spouse during that period.
However, definitions vary by program, and some programs impose additional requirements.
For example, California Dream For All also has first-generation homebuyer requirements that differ from the basic first-time buyer definition.
Before applying for assistance, confirm your eligibility with an approved program lender.
5. Understanding Your Credit Score and Mortgage Qualification
Mortgage lenders evaluate several factors when determining whether to approve a home loan.
These generally include:
- Credit history and credit score.
- Employment and income documentation.
- Existing monthly debt obligations.
- Available assets and cash reserves.
- Down payment amount.
- Property value and mortgage program eligibility.
Your debt-to-income ratio, commonly called DTI, is particularly important. It compares your monthly debt payments with your qualifying gross monthly income.
For example, if your gross monthly income is $12,000 and your combined monthly debt obligations, including the proposed housing payment, equal $4,800, your DTI would be 40%.
The acceptable DTI varies by lender, mortgage program, and overall borrower profile.
How to Improve Your Mortgage Readiness
- Pay existing bills and credit obligations on time.
- Keep credit card balances manageable.
- Review credit reports for errors.
- Avoid unnecessary new debt before closing.
- Maintain organized records of income and assets.
- Discuss large financial transfers or gifts with your lender.
A borrower with strong financial qualifications may qualify for better loan terms, potentially reducing the total cost of homeownership.
6. How Much Are Closing Costs in California?
The down payment is only one component of the cash required to purchase a home.
Closing costs commonly include lender charges, appraisal fees, escrow services, title-related expenses, prepaid insurance, tax adjustments, and other transaction costs.
According to the Consumer Financial Protection Bureau, buyers can use approximately 2% to 5% of the purchase price as an early planning estimate for closing costs, excluding the down payment.
Actual amounts vary considerably depending on the property, financing structure, lender, and negotiated allocation of expenses.
For example, on an $800,000 purchase, a preliminary closing-cost budget using this range would be approximately $16,000 to $40,000.
Buyers should request an individualized Loan Estimate and review the expected cash-to-close amount before committing to a purchase.
7. Get Preapproved Before Shopping for Homes
Mortgage preapproval is an important early step in the home buying process.
During preapproval, a lender reviews financial information and determines the approximate mortgage amount for which the buyer may qualify, subject to applicable conditions.
Preapproval can help buyers understand their purchasing range and demonstrate financial readiness when submitting an offer.
However, preapproval is not a guarantee of final loan approval.
Final approval generally depends on additional underwriting, verification of borrower information, property appraisal, and satisfaction of the lender's conditions.
Buyers should compare offers from multiple lenders and pay attention to the interest rate, annual percentage rate, origination charges, mortgage insurance, and total closing costs.
The Consumer Financial Protection Bureau provides guidance on comparing mortgage Loan Estimates.
8. Choose an Experienced California Real Estate Agent
Working with a knowledgeable real estate agent can be particularly valuable for first-time homebuyers navigating California's competitive housing markets.
An experienced buyer's agent can assist with evaluating comparable properties, understanding market conditions, preparing offers, reviewing disclosures, coordinating inspections, and negotiating contractual terms.
Local knowledge is especially important in Silicon Valley, where property values can vary substantially between neighborhoods and even individual streets.
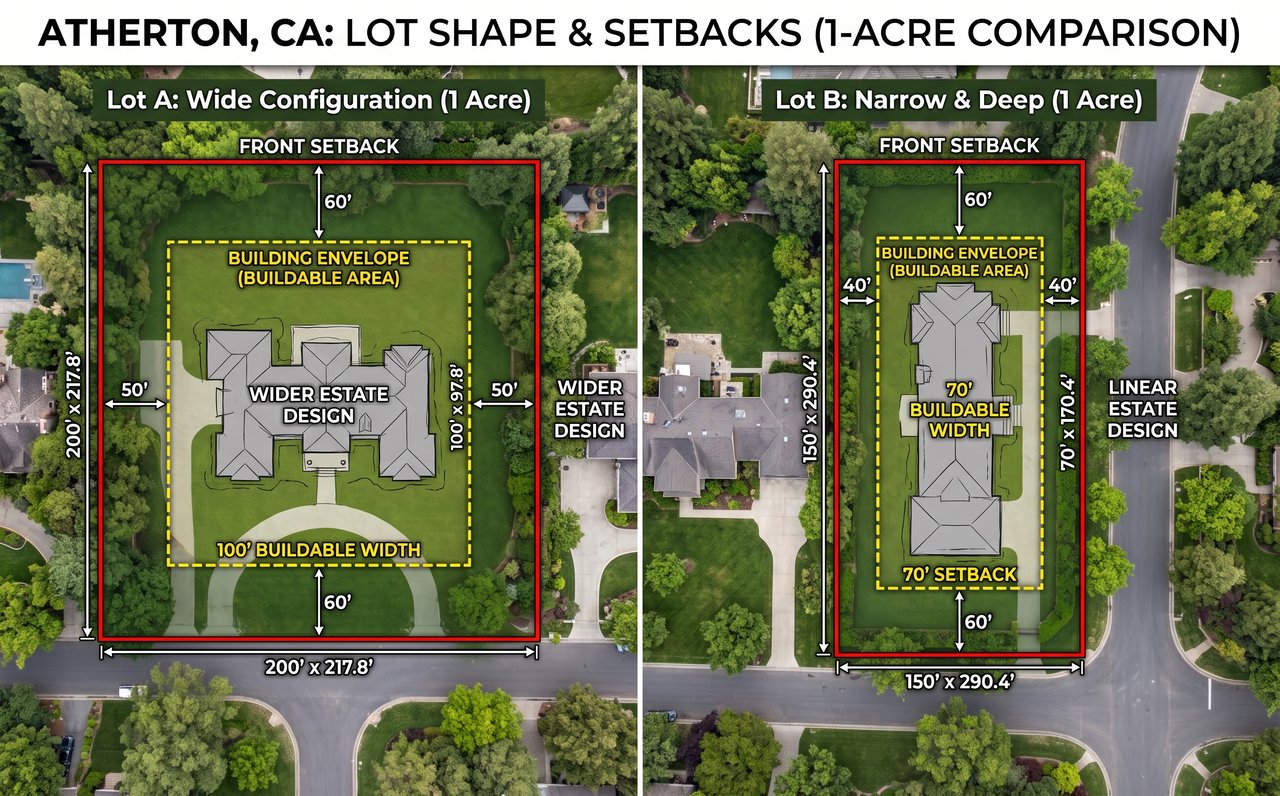
For example, buyers exploring Menlo Park, Palo Alto, or Los Altos real estate should understand how location, lot characteristics, property condition, and development restrictions influence market value.
Understanding California's Buyer-Broker Representation Agreement
Effective January 1, 2025, California law requires written buyer-broker representation agreements when a real estate broker represents a buyer in covered real estate transactions.
Under California Assembly Bill 2992 and implementing regulations, the agreement must generally be executed as soon as practicable, but no later than execution of the buyer's offer. Regulations also establish a rebuttable presumption favoring execution before an agent shows property to the buyer.
The agreement should identify the services provided, compensation terms, when compensation becomes due, and the agreement's duration.
For individual buyers, the initial agreement generally cannot exceed three months, subject to statutory exceptions and renewal provisions.
Buyers should understand these terms before signing, including whether they may have an obligation to pay any portion of their agent's compensation.
Real estate commissions are negotiable and are not set by law.
9. Choose the Right Neighborhood for Your Lifestyle and Budget
Finding the right home involves more than selecting a property with attractive finishes or sufficient square footage.
Buyers should evaluate neighborhood characteristics that matter to their daily lives and long-term plans.
Important considerations may include:
- Commute times and transportation access.
- Proximity to employment centers.
- Schools and verified attendance boundaries.
- Shopping, restaurants, and recreational facilities.
- Traffic, noise, and surrounding land uses.
- Property taxes, insurance costs, and HOA expenses.
- Future development and neighborhood changes.
In Silicon Valley, first-time buyers may find that a condominium or townhome provides a more attainable entry into a desired community than a detached single-family home.
Buyers can explore Palo Alto homes for sale and Los Altos homes for sale to compare housing options and neighborhood characteristics.
10. Search for Homes and Attend Property Showings
Once your financing and purchasing criteria are established, you can begin evaluating available properties.
Online listings, photographs, floor plans, and virtual tours are useful for narrowing your search.
However, buyers should visit properties whenever practical to assess features that may not be apparent online.
During a showing, consider the property's layout, natural light, condition, noise, parking, and surrounding environment.
Look beyond cosmetic improvements and consider whether the home will meet your needs for several years.
For condominiums and townhomes, investigate HOA fees, maintenance responsibilities, insurance arrangements, and governing documents.
11. How to Make an Offer on a House in California
Once you identify a suitable property, your agent can help prepare a written purchase offer.
In California, residential purchase agreements generally address important terms such as:
- Purchase price.
- Initial deposit and escrow instructions.
- Financing terms.
- Investigation, appraisal, and loan contingencies.
- Disclosure obligations.
- Allocation of transaction costs.
- Closing timeline.
- Possession and property condition.
The terms of an offer can be as important as the proposed purchase price.
In competitive markets, buyers may feel pressured to shorten deadlines or waive contingencies. However, waiving contractual protections can create significant financial and legal risks.
First-time buyers should understand the consequences of each contract provision before submitting an offer.
12. Home Inspections and Property Disclosures
Professional inspections are among the most important protections available to a homebuyer.
A general home inspection can help identify visible defects and conditions requiring further evaluation.
Depending on the property, additional inspections may be appropriate for:
- Foundation and structural components.
- Roofing and drainage systems.
- Plumbing and sewer lines.
- Electrical systems.
- Heating and cooling equipment.
- Termites and other wood-destroying organisms.
- Moisture intrusion and water damage.
- Retaining walls and site drainage.
California sellers may be required to provide statutory property disclosures, subject to the nature of the transaction and applicable exemptions.
Buyers should carefully review the Transfer Disclosure Statement, Natural Hazard Disclosure report, available inspection reports, and other relevant documents.
These materials may reveal issues that affect safety, insurability, maintenance costs, or property value.
Buyers should also verify permit records when significant additions, conversions, or renovations have been performed.
13. Why Homeowners Insurance Is Especially Important in California
Homeowners insurance is a critical consideration when purchasing residential property.
In some parts of California, obtaining affordable insurance has become more challenging because of wildfire risk, rebuilding costs, and changes in insurance availability.
Buyers should investigate insurance options early in the transaction rather than assuming coverage will be available at an affordable premium.
A lender will generally require acceptable property insurance before funding a mortgage.
Buyers should obtain quotes and understand the policy's coverage limits, exclusions, deductibles, and rebuilding provisions.
Standard homeowners insurance also generally excludes earthquake damage, making separate earthquake coverage worth evaluating.
The California Department of Insurance provides guidance on residential coverage and insurance availability.
14. Understanding Property Taxes When Buying a California Home
California's Proposition 13 generally establishes a base property tax rate of 1% of assessed value, subject to voter-approved indebtedness and other applicable assessments.
When a property changes ownership, its assessed value is generally reassessed based on the new purchase, subject to applicable exclusions.
Accordingly, buyers should not assume that the current owner's property tax bill represents what they will pay after purchasing the property.
Supplemental property tax assessments may also arise after a change in ownership.
In addition to regular property taxes, some homes may be subject to special assessments, parcel taxes, or Mello-Roos community facilities district charges.
Before closing, buyers should obtain a realistic estimate of the property's expected annual tax obligations.
15. What Happens During Escrow in California?
After a seller accepts a purchase offer, the transaction generally proceeds through escrow.
Escrow is a process in which a neutral third party holds and processes funds, documents, and instructions according to the terms of the transaction.
During escrow, buyers typically complete several important steps:
- Submit the initial deposit according to the purchase agreement.
- Review seller disclosures and property reports.
- Complete applicable property inspections and investigations.
- Work with the lender on mortgage underwriting and appraisal.
- Review preliminary title information and other relevant documents.
- Obtain homeowners insurance.
- Satisfy or address contractual contingencies by the applicable deadlines.
- Review final loan and escrow documents.
- Arrange the required funds for closing.
- Complete the final walkthrough and closing process.
In a financed transaction, the lender generally provides a Closing Disclosure at least three business days before consummation, subject to applicable requirements and exceptions.
Once the required funds and documents are received, the transaction can proceed toward recording of the deed and completion of the purchase.
Buyers should independently verify escrow wiring instructions using a trusted telephone number before transferring funds, because real estate transactions can be targets of wire fraud.
16. Common Mistakes First-Time California Homebuyers Should Avoid
Understanding common purchasing mistakes can help buyers reduce unnecessary risks and expenses.
- Shopping before establishing a budget: Determine your comfortable monthly payment before selecting a price range.
- Assuming 20% down is mandatory: Explore available mortgage and assistance programs.
- Ignoring closing costs: Budget for lender fees, escrow costs, insurance, and other expenses.
- Skipping inspections: Investigate potential defects and maintenance obligations before completing the transaction.
- Overlooking HOA documents: Review assessments, reserves, restrictions, and association financial information when purchasing a condo or planned development property.
- Underestimating property taxes: Calculate the anticipated reassessed value rather than relying on the seller's current tax bill.
- Delaying insurance research: Confirm that the property can be insured on acceptable terms.
- Making major financial changes during escrow: Avoid new debts, unexplained transfers, or employment changes without discussing potential mortgage consequences with your lender.
- Waiving important protections without understanding the risks: Carefully evaluate contingencies and contract deadlines.
17. Is 2026 a Good Time to Buy Your First Home in California?
Whether 2026 is a good time to buy depends on your financial readiness, local housing conditions, and plans for the property.
Mortgage rates, home prices, and inventory levels can change, but attempting to identify the perfect moment to enter the market is difficult.
For buyers who expect to remain in their homes for an extended period, purchasing a suitable property at an affordable monthly cost may be more important than predicting short-term price movements.
In high-cost Silicon Valley communities, buyers should consider whether their budget is better suited to a condominium, townhome, smaller single-family residence, or a neighboring community.
Ultimately, a successful first home purchase begins with financial preparation, careful property evaluation, and realistic expectations.
Frequently Asked Questions About Buying Your First Home in California
Can I buy a house in California with only 3% down?
Yes. Some conventional mortgage programs allow eligible borrowers to purchase a home with as little as 3% down, subject to loan limits, underwriting requirements, and other conditions. Additional closing costs and reserves may also be necessary.
Do I need a 700 credit score to buy a house?
No. Different mortgage programs have different credit requirements. Some FHA loans may permit borrowers with lower credit scores, although lenders can impose additional requirements and less favorable credit profiles may result in higher borrowing costs.
Can I qualify as a first-time buyer if I owned a home several years ago?
Possibly. Many CalHFA programs apply a three-year first-time buyer definition, but exact requirements vary. Buyers should review the eligibility rules for the specific program.
Can first-time homebuyers receive down payment assistance in California?
Yes. CalHFA and certain local or participating lending programs offer down payment or closing cost assistance to qualifying buyers. Some assistance is structured as a repayable loan rather than a grant, and funding may be limited.
How long does buying a home in California take?
The search period varies widely. Once an offer is accepted, escrow may take approximately 30 to 45 days in many financed transactions, although the actual timeline depends on financing, contract terms, inspections, title matters, and other circumstances.
Should I buy a condo or a house as my first property?
A condominium may provide a lower purchase price and reduced direct exterior maintenance, while a detached house may offer greater privacy, land ownership, and flexibility. The appropriate choice depends on your budget, lifestyle, HOA obligations, and long-term plans.
Final Thoughts: Buying Your First Home in California
Buying your first home in California requires careful planning, but the process becomes more manageable when you understand your financing options, purchasing costs, and contractual responsibilities.
Start by evaluating your budget, obtaining mortgage preapproval, and determining whether you qualify for available homebuyer assistance programs.
Then focus on finding a property that meets your needs, carefully reviewing disclosures and inspections, and understanding each stage of the transaction before making major commitments.
Whether you are purchasing a condominium in Palo Alto, a townhome in Menlo Park, or a single-family residence elsewhere in California, thoughtful preparation can help you make a more confident decision.
Buy Your First Home With Milad Real Estate
At Milad Real Estate, we help buyers navigate residential real estate transactions throughout Menlo Park, Palo Alto, Atherton, Los Altos, Woodside, Redwood City, and surrounding Silicon Valley communities.
As both a real estate broker and attorney, Aria Vatankhah brings experience in real estate transactions, contractual matters, and property-related legal considerations.
Whether you are exploring your financing options, comparing neighborhoods, or preparing to make your first offer, Milad Real Estate can help you understand the process and evaluate available opportunities.
Visit Milad Real Estate to explore Silicon Valley properties and learn more about buying a home.
Aria Vatankhah
Founder, Milad Real Estate
Real Estate Broker | Attorney at Law
Phone: 650-799-8168
Email: [email protected]
Sources and additional resources: California Housing Finance Agency — Homebuyer Programs; California Dream For All; California Department of Real Estate — First-Time Buyers; Consumer Financial Protection Bureau — Buying a Home; California Department of Insurance.
Updated November 2026. Mortgage programs, eligibility requirements, assistance funding, and financing terms may change. This article is for general educational purposes and does not constitute individualized legal, tax, lending, or financial advice.